2026 FAFSA Updates: Maximize College Aid for US Families by 15%
Anúncios
Navigating the 2026 FAFSA Updates: A Step-by-Step Guide for United States Families to Maximize College Aid by 15%
The journey to higher education is an exciting, yet often financially daunting, prospect for families across the United States. As college costs continue to rise, financial aid becomes an increasingly critical component of making those dreams a reality. For families with students aspiring to attend college in the 2026-2027 academic year, understanding the upcoming 2026 FAFSA updates is not just recommended; it’s essential. These changes are designed to simplify the application process and, for many, potentially increase eligibility for federal student aid. Our comprehensive guide will walk you through these pivotal changes, offering actionable strategies to help your family maximize college aid by an impressive 15% or more.
The Free Application for Federal Student Aid (FAFSA) is the gateway to federal grants, scholarships, work-study programs, and federal student loans. It’s the primary tool colleges use to determine eligibility for their own institutional aid as well. With the significant FAFSA Simplification Act changes rolling out in phases, the 2026-2027 FAFSA will incorporate further refinements that can directly impact your financial aid package. Staying informed and prepared is your best defense against missing out on crucial funding.
This article will delve deep into what these 2026 FAFSA updates entail, how they differ from previous years, and most importantly, how you can strategically navigate them to secure the best possible financial outcome for your student’s college education. From understanding the new Student Aid Index (SAI) to leveraging changes in asset reporting, we’ll cover every aspect you need to know.
Anúncios
Understanding the FAFSA Simplification Act: A Foundation for 2026 FAFSA Updates
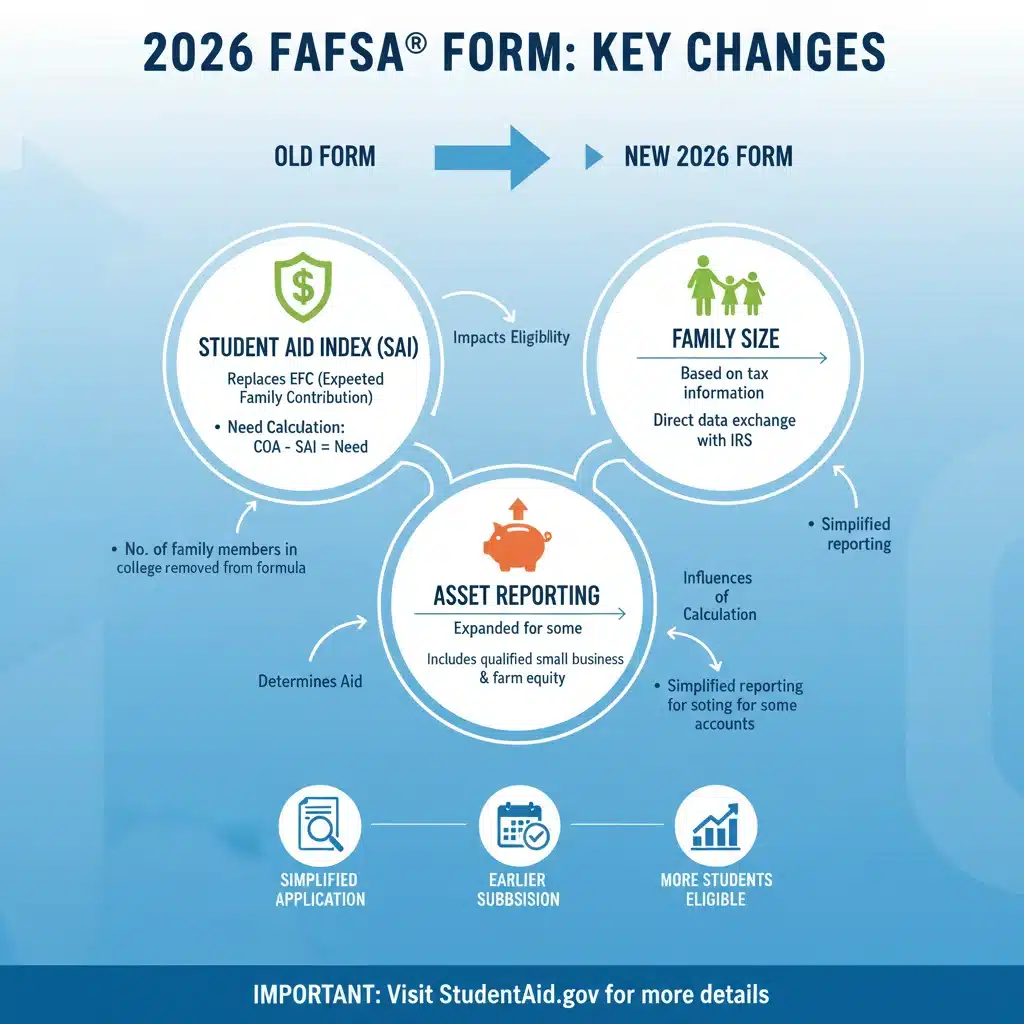
Before we dive into the specifics of the 2026 FAFSA updates, it’s crucial to grasp the broader context of the FAFSA Simplification Act. This landmark legislation, passed in 2020, aims to make the financial aid process less confusing and more accessible. While some changes, like the new FAFSA form design and the shift from Expected Family Contribution (EFC) to the Student Aid Index (SAI), were implemented for the 2024-2025 aid year, subsequent years, including 2026-2027, will see further refinements and clarifications that could significantly impact your aid eligibility.
Key Pillars of FAFSA Simplification
- Simplified Application: The form has been streamlined, reducing the number of questions and making it more user-friendly. This simplification continues to evolve.
- Student Aid Index (SAI): This replaces the Expected Family Contribution (EFC). The SAI is a number used by schools to determine how much federal student aid a student is eligible to receive. A lower SAI generally means more aid.
- Expanded Pell Grant Eligibility: More students are now eligible for Pell Grants, and the maximum award amount can be tied to inflation.
- Changes to Family Size Definition: The definition of family size now aligns with tax household size, which can impact aid calculations.
- Direct Data Exchange with IRS: The requirement for all contributors (student, parents, spouse) to provide consent for direct data exchange with the IRS is a cornerstone of simplification, aiming to reduce errors and streamline income reporting.
The 2026 FAFSA updates will build upon these foundational changes, refining how certain income and asset information is treated and ensuring the new system operates as intended. Families need to be aware that the FAFSA is not a static document; it’s a dynamic application that reflects ongoing efforts to make higher education more affordable.
Anúncios
Major 2026 FAFSA Updates to Watch For
While the core structure introduced by the FAFSA Simplification Act will remain, the 2026-2027 FAFSA cycle will bring specific nuances that families should prioritize. These updates are critical for optimizing your aid potential.
1. Refined Treatment of Small Businesses and Family Farms
One of the most significant changes under the FAFSA Simplification Act, which will be fully operational and understood by the 2026 cycle, involves how small businesses and family farms are assessed. Previously, these assets were often excluded from the EFC calculation if they met certain criteria. Under the new rules, the net worth of a business or farm, regardless of its size, will be included in the asset calculation for the SAI. This change can have a substantial impact on families who own such assets.
- What it means for you: If your family owns a small business or farm, its value will now contribute to your SAI. It’s crucial to understand how this net worth is calculated and to ensure accurate reporting. This might require professional appraisal or careful documentation of business liabilities to present the most accurate financial picture.
- Strategy: Consult with a financial advisor or a tax professional to understand the valuation methods and potential strategies to manage this asset’s impact on your SAI.
2. Changes in Reporting Untaxed Income
The definition and reporting of untaxed income have also been refined. While some untaxed benefits like child support received were previously reported, the 2026 FAFSA updates continue to clarify what types of untaxed income are included in the SAI calculation. This ensures a more consistent and equitable assessment of a family’s financial strength.
- What it means for you: Be meticulous in reporting all sources of income, both taxed and untaxed, as required by the FAFSA. Misreporting can lead to delays or incorrect aid offers.
- Strategy: Keep thorough records of all financial transactions, including any untaxed income sources. When in doubt, err on the side of reporting and seek clarification from the financial aid office.
3. Further Clarifications on Parental Contribution
The FAFSA Simplification Act already made changes to how parental information is used, particularly for divorced or separated parents. The parent who provides the most financial support to the student (rather than the parent with whom the student lives most of the time) is now the one whose information is reported. The 2026 FAFSA updates will likely solidify interpretations and guidance around complex family structures to ensure consistent application.
- What it means for you: If you are a student with divorced or separated parents, ensure you identify the correct parent to report on the FAFSA based on who provides the most financial support.
- Strategy: Discuss this with both parents well in advance of applying to avoid confusion and ensure the correct financial data is submitted.
4. Enhanced Pell Grant Eligibility Formulas
While Pell Grant eligibility was expanded with the initial FAFSA Simplification Act, the 2026 FAFSA updates will continue to refine the formulas used to determine eligibility and award amounts. This includes linking maximum and minimum Pell Grant eligibility to federal poverty levels and inflation, potentially benefiting more low-income families.
- What it means for you: More families may qualify for Pell Grants, or existing recipients might see increased awards.
- Strategy: Even if you didn’t qualify for a Pell Grant in the past, it’s worth reapplying as eligibility criteria are evolving.
Step-by-Step Guide to Maximizing College Aid with the 2026 FAFSA Updates
Now that you understand the key changes, let’s outline a strategic approach to navigate the 2026 FAFSA updates and maximize your financial aid potential. Following these steps can help you secure up to 15% more aid.
Step 1: Early Preparation and Information Gathering (Even Before October 1st)
The FAFSA typically opens on October 1st each year for the following academic year, but preparation should start much earlier. For the 2026-2027 academic year, you’ll be using tax information from 2024.
- Gather 2024 Tax Records: Ensure your 2024 tax returns (Form 1040, W-2s, 1099s, etc.) are completed accurately and on time. The FAFSA will pull this information directly from the IRS via the Direct Data Exchange (DDX), so accuracy is paramount.
- Understand Your Assets: Inventory all family assets, including savings accounts, checking accounts, investments (stocks, bonds, mutual funds, CDs), real estate (excluding the primary residence), and business/farm net worth. Be prepared to report these accurately, especially with the refined treatment of small businesses and farms.
- Create FSA IDs: Both the student and one parent (if the student is dependent) will need an FSA ID (Federal Student Aid ID). This is a username and password used to log in to federal student aid websites. Create these well in advance, as it can take a few days to verify.
- Research College Costs: Understand the estimated Cost of Attendance (COA) for the colleges your student is interested in. This includes tuition, fees, room, board, books, supplies, transportation, and personal expenses. Knowing this helps you gauge the financial gap you’ll need to fill.
Step 2: Understanding the Student Aid Index (SAI) and Its Components
The SAI is the core of your aid eligibility. A lower SAI means more potential aid. Understanding what contributes to it is vital.
- Income: This is the largest factor. It includes both taxed and untaxed income for parents and students. The 2026 FAFSA updates will continue to refine how specific untaxed income sources are treated.
- Assets: Parental assets (excluding primary residence, retirement accounts, and certain life insurance policies) and student assets are considered. The inclusion of small business/farm net worth is a significant change to factor in.
- Family Size: This is now primarily determined by the number of individuals reported on your federal tax return.
- Number of Students in College: Unlike the previous EFC, the SAI formula does NOT divide the parent contribution by the number of children in college. This is a critical change. If you have multiple children in college simultaneously, your overall aid eligibility might be impacted compared to previous years.
Step 3: Strategic Financial Planning to Optimize Your SAI
While you shouldn’t make drastic financial decisions solely for financial aid, understanding how certain assets and income are treated can inform your planning.
- Reduce Reportable Assets: If possible, consider using funds in non-retirement savings accounts to pay down consumer debt (credit cards, car loans) or make necessary home repairs before the FAFSA base year (2024 for the 2026-2027 FAFSA).
- Student Assets vs. Parent Assets: Student assets are assessed at a higher rate (20%) than parent assets (up to 5.64%). If a student has significant savings, consider moving some funds into a 529 plan (which is considered a parental asset if the parent is the owner) or spending it on legitimate educational expenses before applying.
- 529 Plans: Funds in 529 college savings plans are considered parental assets and are assessed at the lower parental rate, making them an efficient way to save for college.
- Timing of Income: If a parent anticipates a large bonus or significant income event, consider if there’s flexibility to receive it outside the FAFSA base income year (e.g., after December 31, 2024, for the 2026-2027 FAFSA).
- Business/Farm Valuation: For families with small businesses or farms, ensure accurate valuation. Document all liabilities against the business/farm to present a true net worth. Consult with an accountant.
Step 4: Completing the 2026 FAFSA Accurately and On Time
Once the FAFSA opens (October 1, 2025, for the 2026-2027 academic year), submit it as soon as possible.
- Use the DDX: Consent to retrieve your tax information directly from the IRS using the Direct Data Exchange (DDX). This minimizes errors and streamlines the process.
- Review Carefully: Even with DDX, review all pre-filled information and manually entered data for accuracy before submitting. Errors can lead to delays or reduced aid.
- Meet Deadlines: Pay close attention to federal, state, and institutional FAFSA deadlines. Some aid is first-come, first-served. Missing a deadline could mean missing out on significant funding.
- List All Schools: List all colleges your student is considering on the FAFSA. Each school will receive your FAFSA data.
Step 5: Reviewing Your Financial Aid Offer and Appealing if Necessary
After submitting the FAFSA, colleges will send financial aid offer letters.
- Compare Offers: Don’t just look at the total aid. Compare grants and scholarships (money you don’t pay back) versus loans (money you do pay back). Look at the net price (Cost of Attendance minus grants/scholarsFhips).
- Understand Loan Types: Differentiate between subsidized (interest paid by government while in school) and unsubsidized loans.
- Appeal if Circumstances Change: If your family’s financial situation has changed significantly since the 2024 tax year (e.g., job loss, medical expenses, divorce), contact the college’s financial aid office. They may be able to make professional judgments to adjust your aid package. This is a critical step for many families to maximize aid. Provide documentation for any appeals.
Step 6: Continuous Monitoring and Reapplication
Financial aid is an annual process.
- Reapply Every Year: You must complete the FAFSA each year your student attends college to remain eligible for federal student aid.
- Stay Informed: Continue to monitor for any further updates or changes to federal financial aid policies, as they can evolve.
Common Pitfalls to Avoid with the 2026 FAFSA Updates
Even with the best intentions, families can make mistakes that hinder their aid potential. Be aware of these common pitfalls:
- Procrastination: Waiting until the last minute can mean missing out on limited funds. Submit early!
- Incorrect Information: Errors, even minor ones, can cause delays or lead to incorrect aid calculations. Double-check everything.
- Not Creating an FSA ID in Advance: This is a common bottleneck. Create it weeks before you plan to fill out the FAFSA.
- Assuming You Won’t Qualify: Many families mistakenly believe they won’t qualify for aid due to their income or assets. The only way to know for sure is to apply. Even if you don’t qualify for need-based grants, you might be eligible for federal student loans, which often have better terms than private loans.
- Ignoring State and Institutional Aid: The FAFSA is primarily for federal aid, but it’s also used by states and colleges to award their own funds. Don’t neglect researching state grant programs and institutional scholarships.
- Not Appealing: If your financial situation changes or you believe your aid package doesn’t reflect your family’s true ability to pay, always consider appealing to the financial aid office.
Conclusion: Empowering Your Family Through the 2026 FAFSA Updates
The 2026 FAFSA updates represent an ongoing evolution in how federal student aid is distributed, aiming for a simpler, more equitable system. While changes can sometimes feel overwhelming, they also present new opportunities for families to secure crucial financial support for higher education. By understanding these updates, meticulously preparing, strategically planning, and submitting your FAFSA accurately and on time, your family can navigate the financial aid landscape with confidence.
Remember, the goal is not just to fill out a form, but to strategically position your family to maximize every available dollar of aid. By following this comprehensive guide, you are well-equipped to understand the nuances of the 2026 FAFSA updates and potentially increase your college aid by 15% or more, paving a smoother path to your student’s academic future. Start preparing today, and empower your student’s educational journey.