Navigating Inflation in 2026: Proven Investment Strategies to Protect Your Savings from a Projected 4% Erosion
The economic landscape is perpetually shifting, and as we look towards 2026, the specter of inflation looms large. Financial experts are projecting a potential 4% erosion of purchasing power, a figure that demands proactive and strategic responses from investors and savers alike. Understanding and implementing effective inflation investment strategies is not merely advisable; it is essential for safeguarding your hard-earned wealth and ensuring your financial future remains robust. This comprehensive guide will delve into the mechanisms of inflation, its potential impact in 2026, and, most importantly, provide you with actionable, proven strategies to protect your savings and even thrive in an inflationary environment.
Anúncios
Understanding the Inflationary Environment of 2026
Before we explore specific investment strategies for inflation, it’s crucial to grasp what inflation truly means and why 2026 is projected to be a challenging year. Inflation, at its core, is the rate at which the general level of prices for goods and services is rising, and consequently, the purchasing power of currency is falling. A 4% erosion means that what 100 dollars buys today will cost 104 dollars next year, effectively diminishing the value of your cash holdings and fixed-income investments.
What Drives Inflation?
Several factors can contribute to inflationary pressures. Demand-pull inflation occurs when aggregate demand in an economy outpaces aggregate supply, driving prices up. Cost-push inflation, on the other hand, happens when the cost of producing goods and services increases, forcing businesses to raise prices. Supply chain disruptions, geopolitical events, fiscal policies (such as government spending), and monetary policies (like interest rate adjustments by central banks) all play significant roles. For 2026, a combination of these factors is anticipated, including continued global supply chain recalibrations, potential wage-price spirals, and the lingering effects of unprecedented fiscal stimulus from previous years. Understanding these drivers is the first step in formulating effective inflation hedges.
The Impact of 4% Inflation on Your Savings
A 4% inflation rate might seem manageable on the surface, but its cumulative effect can be devastating over time. For instance, if you have $100,000 in a savings account earning a paltry 0.5% interest, a 4% inflation rate means your real return is -3.5%. This translates to a loss of $3,500 in purchasing power annually. Over a decade, this seemingly small erosion can significantly reduce the real value of your wealth. This is why passive savings, while offering security, are highly vulnerable to inflation. Active and informed inflation investment strategies 2026 are paramount.
Anúncios
Core Principles of Inflation-Proof Investing
To effectively combat inflation, certain core investment principles must be adopted. These principles form the bedrock upon which specific best investments for inflation are built.
Diversification is Key
Never put all your eggs in one basket, especially in an inflationary environment. Diversifying your portfolio across various asset classes that behave differently during inflation is critical. This includes a mix of equities, real estate, commodities, and inflation-protected securities. A well-diversified portfolio helps mitigate risk and enhances the potential for real returns.
Focus on Real Assets
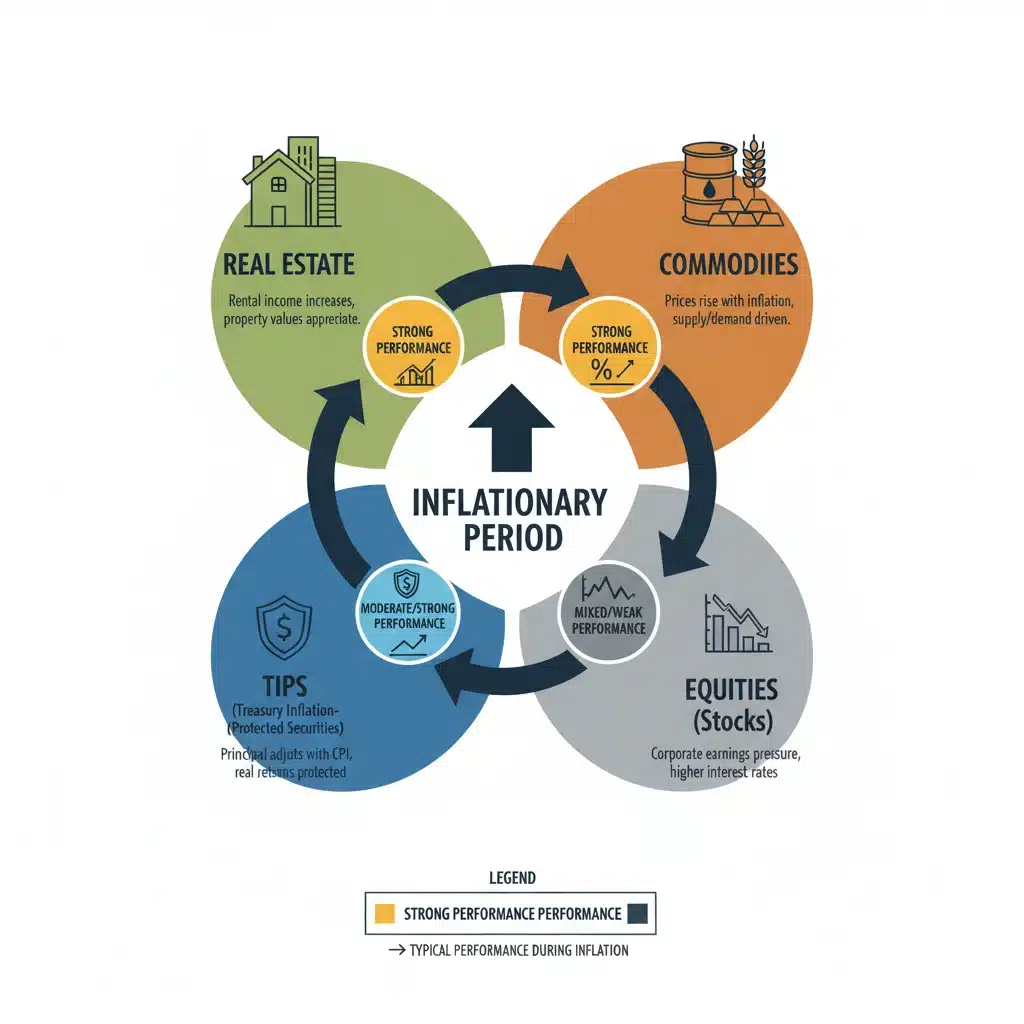
Real assets, by their nature, tend to hold or increase their value during inflationary periods because their intrinsic value is not tied to a depreciating currency. These include physical assets like real estate, commodities, and infrastructure. Unlike financial assets like bonds, which pay fixed income that loses value with inflation, real assets often appreciate as the cost of living rises.
Embrace Growth and Value
While value stocks might seem appealing due to their lower prices, growth stocks, particularly those with strong pricing power and innovative products, can also perform well. Companies that can pass on increased costs to consumers without losing market share are often resilient. Similarly, companies with strong balance sheets and consistent earnings are better positioned to weather economic storms. These considerations are vital when formulating your inflation investment strategies.
Proven Inflation Investment Strategies for 2026
Now, let’s explore specific investment strategies against inflation that can help protect your portfolio in 2026.
1. Real Estate: A Tangible Hedge
Real estate has historically been one of the most reliable hedges against inflation. As the cost of living rises, so too do property values and rental income. This creates a dual benefit: appreciation of the asset itself and increased cash flow from rents, which can be adjusted upwards to keep pace with inflation.
- Residential Real Estate: Owning rental properties can provide a steady stream of inflation-adjusted income. Mortgage payments, if fixed, become cheaper in real terms as inflation erodes the value of money.
- Commercial Real Estate: Similar to residential, commercial properties with inflation-linked leases can be excellent investments.
- REITs (Real Estate Investment Trusts): For those who prefer liquidity and professional management, REITs offer exposure to real estate without direct ownership. They trade like stocks and are required to distribute a significant portion of their income to shareholders.
2. Commodities: Intrinsic Value and Scarcity
Commodities are raw materials like oil, gold, silver, industrial metals, and agricultural products. Their prices often rise with inflation because they are fundamental inputs into the economy. As the cost of production increases, so does the price of the commodity.
- Gold and Silver: Often considered safe-haven assets, gold and silver tend to retain their value during economic uncertainty and inflationary periods. They offer a store of value when fiat currencies are depreciating.
- Energy (Oil, Natural Gas): As energy costs are a significant component of overall inflation, investing in energy-related commodities or companies can provide a hedge.
- Agricultural Products: Food prices are directly impacted by inflation. Futures contracts or ETFs focused on agricultural commodities can be a way to participate.
Investing in commodities can be done through direct ownership (though often impractical for individual investors), futures contracts, or more commonly, through Exchange Traded Funds (ETFs) that track commodity indices. These are powerful inflation investment strategies.
3. Treasury Inflation-Protected Securities (TIPS): Direct Inflation Protection
TIPS are government-issued bonds specifically designed to protect investors from inflation. The principal value of TIPS adjusts with the Consumer Price Index (CPI), meaning it increases with inflation and decreases with deflation. When the bond matures, you receive either the original or adjusted principal, whichever is greater. You also receive semi-annual interest payments, which are paid on the adjusted principal, thus increasing with inflation.
- How they work: If inflation rises, the principal value of your TIPS increases, and so do your interest payments. This provides a direct and reliable hedge against inflation.
- Benefits: Guaranteed by the U.S. government (or equivalent sovereign entity), making them very low risk. They offer a clear mechanism for preserving purchasing power.
- Considerations: While excellent for inflation protection, their real yield (yield above inflation) can be low, and they may underperform in periods of disinflation or deflation.
4. Equities: Companies with Pricing Power and Strong Fundamentals
Not all stocks perform equally well during inflation. The key is to identify companies that possess ‘pricing power’ – the ability to raise their prices without significantly impacting demand for their products or services. These are typically companies with strong brands, essential products, or dominant market positions.
- Consumer Staples: Companies selling essential goods (food, beverages, household products) often have pricing power because consumers continue to buy their products regardless of price increases.
- Utilities: These are often regulated monopolies that can pass on higher costs to consumers, though their growth potential might be limited.
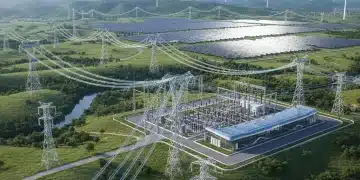
- Infrastructure Companies: Companies involved in building and maintaining essential infrastructure (roads, bridges, utilities) can benefit from increased government spending and inflation-adjusted contracts.
- Companies with Low Debt: High debt levels become more burdensome as interest rates rise in response to inflation. Companies with strong balance sheets are better positioned.
- Dividend Growth Stocks: Companies that consistently grow their dividends can provide an increasing income stream that helps combat inflation’s erosion of purchasing power.
Careful stock selection is a critical component of successful inflation investment strategies in the equity market.
5. Floating-Rate Securities: Adapting to Rate Hikes
As central banks typically raise interest rates to combat inflation, fixed-rate bonds can suffer. Floating-rate securities, such as floating-rate notes or bank loans, have interest payments that adjust periodically based on a benchmark rate (like LIBOR or SOFR). This means their income stream increases as interest rates rise, making them less susceptible to interest rate risk and more attractive in an inflationary environment.
- Floating-Rate Notes (FRNs): These bonds have variable interest rates that are reset periodically.
- Bank Loans (Leveraged Loans): These are loans made to companies that typically have floating interest rates. They can be accessed through mutual funds or ETFs.
Advanced Inflation Investment Strategies for Savvy Investors
Beyond the fundamental approaches, more advanced advanced inflation strategies can further enhance your portfolio’s resilience.
Short-Term Bonds and Cash Equivalents (Strategic Use)
While cash loses value to inflation, holding some short-term bonds or cash equivalents can be strategic. As interest rates rise to combat inflation, new short-term bonds will offer higher yields. This allows investors to reinvest maturing short-term holdings into higher-yielding instruments, effectively capturing the rising rate environment. This isn’t a direct hedge but a tactical approach to liquidity management within inflation investment strategies.
Alternative Investments: Private Equity and Hedge Funds
For accredited investors, private equity and certain hedge fund strategies can offer inflation protection. Private equity investments in real assets or companies with strong pricing power can perform well. Some hedge funds employ strategies specifically designed to profit from inflationary trends or market volatility. However, these investments often come with higher fees, illiquidity, and increased risk.
Investing in Emerging Markets (Selective)
Some emerging markets, particularly those rich in commodities, can benefit from rising commodity prices during global inflationary periods. However, this strategy carries higher geopolitical and currency risks and requires thorough research and a selective approach. It’s an aggressive component of global inflation strategies.
Building Your Inflation-Resistant Portfolio for 2026
Crafting an inflation-resistant portfolio requires a personalized approach. Your risk tolerance, investment horizon, and financial goals will dictate the optimal allocation of assets.
Assess Your Current Portfolio
Start by analyzing your existing investments. How much exposure do you have to fixed-income assets that are vulnerable to inflation? Are you sufficiently diversified in real assets and equities with pricing power? A thorough review will highlight areas that need adjustment within your inflation investment strategies.
Rebalance and Reallocate
Based on your assessment, consider rebalancing your portfolio. This might involve reducing exposure to long-term fixed-rate bonds and increasing allocations to real estate, commodities, TIPS, and carefully selected equities. Remember, rebalancing should be a continuous process, not a one-time event, especially in volatile economic climates.
Consider Professional Guidance
Navigating an inflationary environment can be complex. Consulting with a qualified financial advisor can provide personalized insights and help you tailor personalized inflation strategies that align with your specific situation. An advisor can help you understand the nuances of various investment vehicles and construct a robust portfolio.
The Role of Active Management and Continuous Monitoring
In an inflationary environment, passive investing might not be sufficient. Active management and continuous monitoring of your portfolio are crucial. Economic indicators, central bank policies, and global events can rapidly change, necessitating timely adjustments to your inflation investment strategies.
Stay Informed
Keep abreast of economic news, inflation reports (like CPI and PPI), interest rate decisions, and geopolitical developments. These factors directly influence inflation and the performance of your investments. Knowledge is power when it comes to protecting your wealth.
Regularly Review Performance
Periodically review the performance of your inflation hedges. Are they performing as expected? Are there new opportunities or risks emerging that warrant a change in your strategy? This proactive approach ensures your portfolio remains optimized for the prevailing economic conditions.
Be Agile and Adaptable
The future is uncertain. While we project a 4% inflation erosion for 2026, actual figures could vary. Your inflation investment strategies should be agile enough to adapt to unexpected shifts. This might mean adjusting your commodity exposure, re-evaluating your equity holdings, or modifying your allocation to TIPS based on real-time data.
Beyond Investments: Personal Finance Strategies Against Inflation
While investment strategies are paramount, personal finance decisions also play a crucial role in mitigating the impact of inflation.
Manage Debt Wisely
Fixed-rate debt, such as a traditional mortgage, can become cheaper in real terms as inflation erodes the value of money. However, variable-rate debt can become more expensive as interest rates rise. Prioritize paying down high-interest, variable-rate debt. This is a key personal finance aspect of effective inflation management.
Increase Income and Reduce Expenses
Look for opportunities to increase your income, whether through salary negotiations, side hustles, or skill development. Simultaneously, critically evaluate your expenses and identify areas where you can cut back. Every dollar saved or earned retains more purchasing power when strategically invested or used to reduce debt.
Build an Emergency Fund
An adequately funded emergency reserve, ideally in a high-yield savings account or short-term Treasury bills, provides a buffer against unexpected expenses without forcing you to liquidate long-term investments at inopportune times. While inflation erodes its value, the liquidity and security it offers are invaluable.
Invest in Yourself
Enhancing your skills and education can increase your earning potential, which is one of the most effective long-term hedges against inflation. Your human capital is a powerful asset that can generate higher income streams to offset rising costs. This is an often-overlooked but vital aspect of holistic inflation investment strategies.
Conclusion: Proactive Measures for 2026 and Beyond
The projected 4% inflation erosion in 2026 presents a significant challenge, but it is one that can be navigated successfully with informed and proactive inflation investment strategies. By understanding the drivers of inflation, diversifying your portfolio into real assets and inflation-protected securities, carefully selecting equities with pricing power, and maintaining an agile approach to portfolio management, you can not only protect your savings but also position yourself for potential growth.
Remember, financial planning is an ongoing journey. The strategies outlined here provide a robust framework, but continuous learning, regular review, and professional guidance are your best allies in maintaining financial resilience in an ever-changing economic world. Take action today to ensure your wealth is protected against the inflationary pressures of 2026 and beyond.