Maximize Your 401(k) 2026: New Limits & $1,500 Extra Savings
Anúncios
As the calendar pages turn towards 2026, a crucial window of opportunity opens for millions of Americans focused on securing their financial future: maximizing their 401(k) contributions. For many, the 401(k) is the cornerstone of their retirement strategy, offering significant tax advantages and the potential for substantial long-term growth. Understanding and strategically utilizing the new 401k contribution limits for 2026 isn’t just about hitting a number; it’s about optimizing your path to a comfortable retirement, potentially adding an extra $1,500 or more to your nest egg.
The Internal Revenue Service (IRS) typically announces adjustments to retirement plan contribution limits annually, reflecting inflation and other economic factors. These changes are vital because they directly impact how much you can contribute on a tax-advantaged basis. For 2026, financial experts anticipate an increase in the standard 401(k) contribution limit, as well as the catch-up contribution limit for those aged 50 and over. While official figures are usually released later in the year, proactive planning based on historical trends and economic forecasts can put you ahead of the curve.
Anúncios
This comprehensive guide will delve into the anticipated 401k contribution limits for 2026, providing you with the knowledge and strategies to fully leverage these changes. We’ll explore how to integrate these new limits into your financial planning, discuss the power of employer matching contributions, explain the benefits of catch-up contributions, and offer advanced tactics to supercharge your retirement savings. Our goal is to empower you to not just meet, but exceed your retirement savings goals, ensuring a more secure and prosperous future.
Understanding the Anticipated 401(k) Contribution Limits for 2026
While the official 401k contribution limits for 2026 are yet to be formally announced by the IRS, we can make informed projections based on historical data and current economic indicators. Typically, these limits are adjusted for inflation, using a formula that considers the Consumer Price Index for All Urban Consumers (CPI-U). Given recent inflationary pressures, it’s highly probable that we will see an upward adjustment for the upcoming year.
Projected Standard 401(k) Contribution Limit
For 2025, the standard 401(k) contribution limit for employees is $23,000. Based on inflation trends, it is reasonable to anticipate an increase for 2026. A conservative estimate might place the new limit somewhere between $23,500 and $24,500. This increase, even if seemingly modest, can have a significant cumulative effect over many years, thanks to the power of compounding. For example, an extra $1,000 contributed annually over 20 years, assuming an average 7% return, could add over $40,000 to your retirement nest egg.
Anúncios
Projected Catch-Up Contribution Limit (Age 50 and Over)
The catch-up contribution is a vital provision for individuals aged 50 and older, allowing them to contribute an additional amount beyond the standard limit. This is designed to help those closer to retirement boost their savings. For 2025, the catch-up contribution limit is $7,500. We can expect this figure to also see an increase for 2026, potentially reaching $8,000 or even slightly higher. This additional contribution avenue is a game-changer for older workers, providing a powerful tool to bridge any savings gaps.
Why These Limits Matter
These limits are not merely arbitrary figures; they represent the maximum amount of pre-tax (or Roth, depending on your plan) income you can shield from current taxation, allowing your investments to grow tax-deferred (or tax-free in the case of Roth 401(k)s). Maximizing your contributions up to these limits is one of the most effective ways to reduce your taxable income in the present while building substantial wealth for the future. Ignoring these limits means leaving potential tax savings and compounded growth on the table.
Strategies to Maximize Your 401(k) Contributions in 2026
Simply knowing the new 401k contribution limits isn’t enough; you need a strategic plan to reach them. Here are actionable steps to ensure you’re making the most of your retirement savings opportunities in 2026.
1. Automate and Increase Your Contributions
The easiest way to ensure you hit the new limits is to automate your contributions. Review your current payroll deductions and adjust them to reflect the higher 2026 limits as soon as they are confirmed. If you currently contribute a fixed percentage, consider increasing it. If you contribute a fixed dollar amount, calculate the new monthly or bi-weekly deduction required to reach the maximum annual limit. Many financial advisors recommend increasing your contribution percentage by at least 1% each year until you reach the maximum or a comfortable level.
2. Don’t Leave Employer Matching Money on the Table
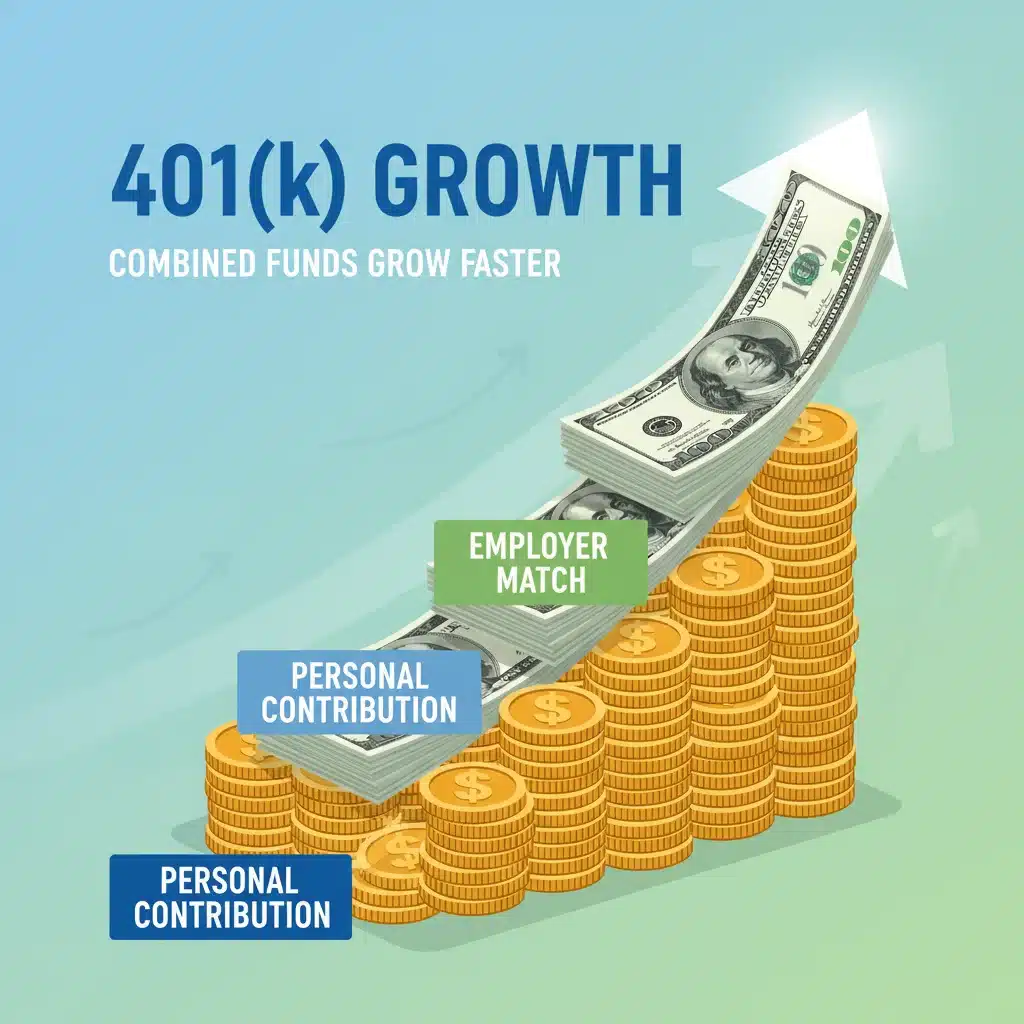
This is arguably the most crucial strategy. Many employers offer a matching contribution, effectively providing free money towards your retirement. For example, an employer might match 50% of your contributions up to 6% of your salary. If you don’t contribute at least 6%, you’re missing out on a guaranteed return on investment. Always aim to contribute at least enough to receive the full employer match. This can significantly boost your overall 401k contribution limits impact without requiring additional effort beyond your initial setup.
3. Leverage Catch-Up Contributions (Age 50+)
If you are aged 50 or older by the end of 2026, you are eligible for catch-up contributions. This additional amount, projected to be around $8,000, can make a monumental difference in your retirement savings. If you haven’t been able to maximize your 401(k) in earlier years, this is your chance to accelerate your savings. Combine the standard limit with the catch-up limit, and you could be contributing over $30,000 annually on a tax-advantaged basis.
4. "Found Money" Strategy: Bonuses, Raises, and Tax Refunds
Consider directing any "found money" towards your 401(k). This includes annual bonuses, salary raises, or tax refunds. Instead of spending these windfalls, funnel them directly into your retirement account. If you receive a raise, commit to contributing at least half of the increase to your 401(k) before you even get used to the extra income. This strategy allows you to increase your contributions without feeling a significant pinch in your take-home pay.
5. Rebalance Your Budget
Take a critical look at your monthly budget. Are there areas where you can cut back to free up more funds for your 401(k)? Even small adjustments, like reducing dining out frequency or canceling unused subscriptions, can add up over time. Prioritizing retirement savings often requires making conscious choices about discretionary spending.
The Power of Compounding: How an Extra $1,500 Makes a Difference
Let’s illustrate the profound impact of consistently maximizing your 401k contribution limits, specifically focusing on how an extra $1,500 annually can significantly enhance your retirement outlook. This extra $1,500 could come from the anticipated increase in the standard contribution limit, a portion of your employer match, or by strategically utilizing the catch-up provision.
Scenario: Adding $1,500 Annually
Imagine you consistently contribute an additional $1,500 to your 401(k) each year, beyond what you would have contributed otherwise. Let’s assume an average annual return of 7% (a reasonable historical average for a diversified portfolio).
- Over 10 Years: An extra $1,500 per year would amount to $15,000 in direct contributions. With a 7% annual return, this additional savings could grow to approximately $22,000.
- Over 20 Years: The direct contributions would be $30,000. Compounded at 7%, this could blossom into roughly $61,500.
- Over 30 Years: Direct contributions of $45,000 could swell to an impressive $152,000.
These figures clearly demonstrate the exponential power of compounding. The earlier you start and the more consistently you contribute, the more time your money has to grow, making even seemingly small annual increases incredibly impactful over the long term. This "extra $1,500" isn’t just a number; it’s a significant boost to your financial security in retirement.
Understanding Your 401(k) Investment Options
Maximizing your 401k contribution limits is only one part of the equation; how your money is invested within the plan is equally crucial. Most 401(k) plans offer a range of investment options, typically mutual funds, exchange-traded funds (ETFs), or target-date funds.
Diversification is Key
Ensure your investments are well-diversified across different asset classes (e.g., stocks, bonds, real estate) and geographies. Diversification helps mitigate risk and can lead to more stable returns over time. Avoid putting all your eggs in one basket.
Risk Tolerance and Time Horizon
Your investment choices should align with your risk tolerance and time horizon. If you are young and have many years until retirement, you can typically afford to take on more risk (e.g., a higher allocation to stocks) for potentially higher returns. As you get closer to retirement, you might consider shifting to a more conservative allocation to protect your accumulated capital.
Target-Date Funds
For those who prefer a hands-off approach, target-date funds can be an excellent option. These funds automatically adjust their asset allocation over time, becoming more conservative as you approach the target retirement date. They offer a professionally managed, diversified portfolio tailored to a specific time horizon.
Review and Rebalance Regularly
It’s vital to periodically review your 401(k) investments, at least once a year, or whenever there are significant life changes or market shifts. Rebalancing involves adjusting your portfolio back to your desired asset allocation. For instance, if stocks have performed exceptionally well, their percentage in your portfolio might have grown beyond your target. Rebalancing would involve selling some stocks and buying more bonds to restore your original allocation.
Roth 401(k) vs. Traditional 401(k): Which is Right for You?
When contributing to your 401(k), you often have a choice between a traditional 401(k) and a Roth 401(k), if your employer offers both. Understanding the differences is critical for optimizing your tax strategy in conjunction with the 401k contribution limits.
Traditional 401(k)
- Tax Treatment: Contributions are made with pre-tax dollars, meaning they reduce your current taxable income. Your investments grow tax-deferred, and you pay taxes on withdrawals in retirement.
- Best For: Individuals who expect to be in a higher tax bracket during their working years than in retirement. The upfront tax deduction is more valuable to them.
Roth 401(k)
- Tax Treatment: Contributions are made with after-tax dollars, meaning they do not reduce your current taxable income. However, qualified withdrawals in retirement are completely tax-free.
- Best For: Individuals who expect to be in a similar or higher tax bracket in retirement than they are now. Paying taxes now at a lower rate can be advantageous. Also beneficial for those who anticipate future tax rate increases.
Making the Choice
The decision between a Traditional and Roth 401(k) depends on your current income, projected retirement income, and your outlook on future tax rates. Many financial experts suggest a diversified approach, contributing to both pre-tax (Traditional 401(k)) and after-tax (Roth 401(k) or Roth IRA) accounts to provide flexibility in retirement. Consult with a financial advisor to determine the best strategy for your individual circumstances.
Beyond the 401(k): Other Retirement Savings Vehicles
While maximizing your 401k contribution limits is paramount, it’s essential to remember that it’s just one piece of the retirement planning puzzle. For those who hit the maximum 401(k) limits, or for those whose employers don’t offer a 401(k), other retirement savings vehicles can complement your strategy.
Individual Retirement Accounts (IRAs)
IRAs (Traditional or Roth) offer another excellent way to save for retirement with tax advantages. The contribution limits for IRAs are separate from 401(k) limits. For 2025, the IRA contribution limit is $7,000, with an additional $1,000 catch-up contribution for those aged 50 and over. These limits are also subject to annual adjustments.
- Traditional IRA: Contributions may be tax-deductible, and earnings grow tax-deferred.
- Roth IRA: Contributions are made with after-tax dollars, and qualified withdrawals in retirement are tax-free.
Eligibility for deducting Traditional IRA contributions and contributing to a Roth IRA can be subject to income limitations, especially if you are also covered by a workplace retirement plan.
Health Savings Accounts (HSAs)
If you have a high-deductible health plan (HDHP), you might be eligible for an HSA. HSAs are often referred to as "triple tax-advantaged" accounts:
- Contributions are tax-deductible.
- Earnings grow tax-free.
- Qualified withdrawals for medical expenses are tax-free.
After age 65, HSA funds can be withdrawn for any purpose without penalty, though non-medical withdrawals will be taxed as ordinary income. This makes HSAs a powerful, albeit often overlooked, retirement savings tool.
Taxable Brokerage Accounts
For those who have maxed out all their tax-advantaged accounts, a standard taxable brokerage account is the next step. While contributions are not tax-deductible and earnings are subject to capital gains taxes, these accounts offer unlimited contribution potential and complete flexibility regarding withdrawals. They can be a great way to save for both short-term and long-term goals.
The Importance of Regular Financial Review and Professional Advice
Navigating the complexities of retirement planning, including understanding and utilizing 401k contribution limits, requires ongoing attention. Your financial situation, goals, and even tax laws can change over time, necessitating adjustments to your strategy.
Annual Financial Check-Up
Make it a habit to conduct an annual financial check-up. This involves reviewing your budget, assessing your investment performance, adjusting your contribution amounts, and ensuring your asset allocation still aligns with your risk tolerance and time horizon. This is also the time to factor in any new 401(k) limits announced by the IRS.
Consulting a Financial Advisor
For many, the guidance of a qualified financial advisor can be invaluable. An advisor can help you:
- Understand the nuances of 401k contribution limits and other retirement vehicles.
- Develop a personalized retirement plan tailored to your specific goals and circumstances.
- Optimize your investment strategy within your 401(k) and other accounts.
- Navigate complex financial decisions, such as Roth conversions or Social Security claiming strategies.
- Stay disciplined and on track with your savings goals.
Even if you are financially savvy, a professional can offer an objective perspective and identify opportunities or risks you might overlook.
Conclusion: Take Control of Your Retirement Future
As we look forward to 2026, the anticipated adjustments to 401k contribution limits present a prime opportunity to supercharge your retirement savings. By understanding these limits, strategically increasing your contributions, leveraging employer matches, and utilizing catch-up provisions, you can significantly enhance your financial security in retirement. Remember, even an extra $1,500 contributed annually can compound into a substantial sum over time, illustrating the profound impact of consistent, disciplined savings.
Don’t wait for the official announcements to start planning. Begin by reviewing your current contributions, assessing your budget, and considering how you can allocate more towards your 401(k). Whether you’re just starting your career or nearing retirement, proactive planning and consistent effort are the keys to building a robust retirement nest egg. Take control of your financial future today, and make 2026 the year you truly maximize your 401(k).