Federal Reserve Interest Rate Hike: Housing Market Impact Explained
Urgent Update: Federal Reserve’s Latest Interest Rate Decision and Its Immediate Impact on Housing Market by 3%
The financial world is abuzz with the Federal Reserve’s recent announcement regarding a significant shift in interest rates. This is not just a headline for economists and Wall Street traders; it’s a critical development with immediate and profound implications for everyday Americans, particularly those involved in or contemplating entering the housing market. The reverberations of this decision are already being felt, with experts projecting an immediate 3% impact on various facets of the housing market. Understanding this urgent update is paramount for homeowners, potential buyers, sellers, and real estate investors alike.
The Federal Reserve, often referred to as ‘the Fed,’ plays a pivotal role in steering the nation’s economic course. Its primary tools for achieving its dual mandate of maximum employment and price stability include setting the federal funds rate. This benchmark rate, while not directly what consumers pay, influences a cascade of other interest rates throughout the economy, most notably mortgage rates. When the Fed raises rates, it effectively makes borrowing more expensive across the board, which can cool down an overheating economy and combat inflation. However, the ripple effect on sectors like housing is often immediate and substantial, creating a new landscape for all participants.
Understanding the Federal Reserve’s Decision: Why Now?
The Federal Reserve’s decision to adjust interest rates is never made lightly. It’s the culmination of careful analysis of a multitude of economic indicators, including inflation rates, employment data, consumer spending, and global economic conditions. In recent months, persistent inflationary pressures have been a primary concern for policymakers. Supply chain disruptions, robust consumer demand, and geopolitical events have all contributed to rising prices for goods and services, eroding purchasing power. To rein in this inflation, the Fed has opted for a more aggressive stance, utilizing interest rate hikes as its primary weapon.
The ‘why now’ question is often tied to the Fed’s assessment of the economy’s capacity to absorb higher borrowing costs without tipping into recession. There’s a delicate balance to strike: curb inflation without stifling economic growth. However, the current economic climate, characterized by strong employment numbers and sustained consumer spending despite inflationary headwinds, has provided the Fed with the necessary impetus to act. This proactive approach aims to prevent inflation from becoming entrenched, which could lead to more severe economic consequences down the line. The immediate 3% impact on the housing market is a direct consequence of this strategic move, designed to cool demand and stabilize prices, albeit with significant short-term adjustments for market participants.
The Immediate 3% Impact on Mortgage Rates and Affordability
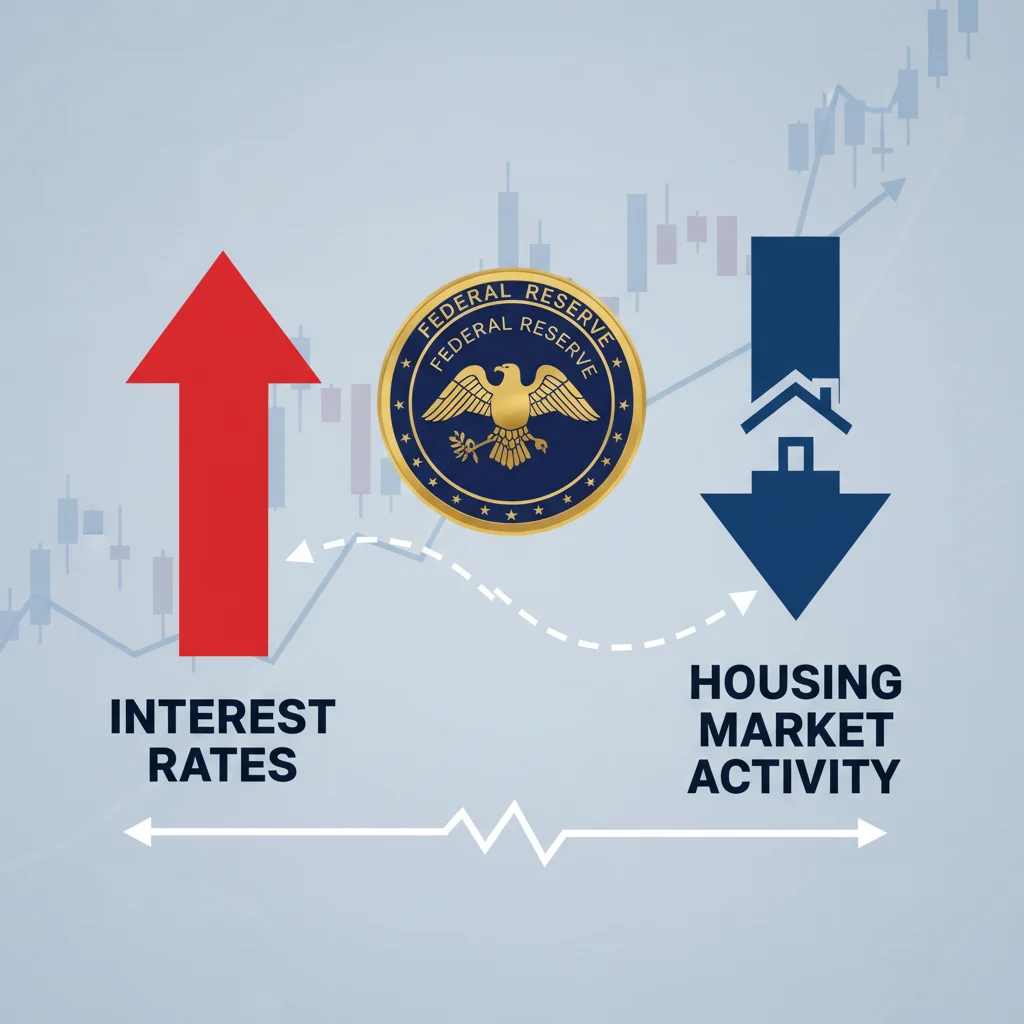
Perhaps the most direct and immediate consequence of the Federal Reserve’s interest rate hike is its effect on mortgage rates. While the federal funds rate is an overnight lending rate between banks, it significantly influences the prime rate, which in turn affects adjustable-rate mortgages (ARMs) and, less directly but still powerfully, fixed-rate mortgages. The market often anticipates Fed moves, and lenders adjust their rates in response to both current announcements and future expectations. This latest hike has already translated into a noticeable increase in the cost of borrowing for homebuyers, leading to an estimated 3% immediate impact on overall housing affordability.
For potential homebuyers, this means that the monthly payments for the same loan amount will be higher. For example, a 3% increase in mortgage rates on a $400,000 home loan can add hundreds of dollars to a monthly payment, significantly reducing purchasing power. This shift can price out a segment of potential buyers, especially first-time buyers who are already grappling with high home prices and limited inventory. The affordability crunch becomes more acute, forcing some to reconsider their homeownership aspirations, delay their plans, or look for less expensive properties. This contraction in buyer demand is a natural outcome of higher borrowing costs and is a key mechanism through which the Fed aims to cool the housing market.
Existing homeowners with adjustable-rate mortgages will also feel the pinch as their interest rates reset, leading to higher monthly payments. While fixed-rate mortgage holders are insulated from immediate changes, the broader market dynamics, including property values, will still affect them. The overall sentiment in the housing market shifts, creating a more cautious environment where both buyers and sellers must re-evaluate their strategies. The 3% impact is not just a number; it represents a tangible increase in the financial burden associated with homeownership and a recalibration of market expectations.
How Sellers and Home Values Are Affected
The Federal Reserve’s interest rate decision has a multifaceted impact on sellers and overall home values. When mortgage rates rise, the pool of eligible buyers shrinks, and those who remain in the market often have reduced purchasing power. This dynamic inevitably leads to a slowdown in market activity. Homes may stay on the market longer, and sellers might need to adjust their price expectations to attract buyers in a less competitive environment. The days of multiple, over-asking-price offers might become less common, particularly in areas that have experienced significant appreciation.
While a 3% immediate impact on home values might seem dramatic, it’s more accurate to view it as a shift in market equilibrium rather than an outright crash. In many overheated markets, home values have seen unsustainable growth over the past few years. Higher interest rates can act as a natural brake, bringing prices back to a more sustainable level. This doesn’t necessarily mean widespread depreciation; rather, it suggests a moderation in the pace of appreciation or, in some cases, slight price corrections. Sellers who were hoping to capitalize on peak market conditions may find themselves needing to be more flexible and realistic with their pricing strategies.
Furthermore, the psychological impact on sellers cannot be understated. A perception of a cooling market can lead to a rush to sell before prices potentially decline further, increasing inventory and further shifting the balance of power from sellers to buyers. This is a critical period for sellers to work closely with real estate professionals to understand local market nuances and develop effective pricing and marketing strategies that align with the new economic reality. The 3% impact on the housing market signals a transition from a seller’s market to a more balanced, or even buyer-friendly, environment in certain regions.
Implications for Real Estate Investors and Developers
Real estate investors and developers are also keenly watching the Federal Reserve’s moves, as interest rate hikes significantly alter their financial models and investment strategies. For investors, higher borrowing costs mean that the cost of capital for acquiring properties increases, potentially reducing their profit margins. This is particularly true for investors who rely on leverage (borrowed money) to finance their purchases. A 3% increase in financing costs can make many previously attractive deals financially unfeasible.
Developers face similar challenges. The cost of construction loans rises, making new projects more expensive to undertake. This can lead to a slowdown in new housing starts, which, paradoxically, could exacerbate supply shortages in the long run if demand eventually picks up again. However, in the short term, higher interest rates are designed to temper demand, making developers more cautious about launching new large-scale projects. The risk-reward calculus shifts, and only the most robust and well-capitalized projects may proceed.
Moreover, the rental market can also see indirect impacts. If homeownership becomes less accessible due to higher mortgage rates, more people may remain in the rental market, potentially driving up rental demand and prices. This could present opportunities for investors focused on rental properties, but they too must contend with higher acquisition costs. The immediate 3% impact on the housing market forces investors and developers to re-evaluate their portfolios, adjust their risk assessments, and explore alternative financing or investment strategies to navigate the changing economic landscape effectively. Long-term investment horizons and diversified portfolios become even more crucial in such volatile times.
Navigating the New Housing Market Landscape: Advice for Buyers
For prospective homebuyers, the Federal Reserve’s interest rate hike fundamentally reshapes the purchasing journey. The immediate 3% impact on borrowing costs means that a thorough re-evaluation of personal finances and market expectations is essential. Here’s some advice to navigate this new landscape:
- Re-evaluate Your Budget: With higher mortgage rates, your purchasing power has likely decreased. It’s crucial to recalculate what you can comfortably afford, factoring in the increased monthly payments. Don’t just look at the sticker price of a home; focus on the total monthly housing cost, including principal, interest, taxes, and insurance (PITI).
- Strengthen Your Financial Position: Lenders will be scrutinizing applications more closely. Work on improving your credit score and increasing your down payment to secure the most favorable interest rates possible. A larger down payment can also reduce the amount you need to borrow, thereby mitigating the impact of higher rates.
- Shop Around for Lenders: Interest rates can vary significantly between different lenders. Don’t settle for the first offer you receive. Get quotes from multiple banks, credit unions, and mortgage brokers to find the most competitive rate and terms. Even a slight difference in interest rates can save you thousands over the life of a loan.
- Consider Adjustable-Rate Mortgages (ARMs) Carefully: While ARMs might offer lower initial rates, they come with the risk of future rate increases. Understand the terms, caps, and potential payment adjustments before committing to an ARM, especially in a rising rate environment.
- Be Patient and Strategic: The market is cooling, which might mean less competition and more negotiation power for buyers. Don’t rush into a purchase. Take your time to find the right property at the right price, and be prepared to negotiate.
- Work with a Knowledgeable Real Estate Agent: An experienced agent can provide valuable insights into local market conditions, help you identify good opportunities, and guide you through the negotiation process.
The key is to approach the market with caution, informed decisions, and a clear understanding of your financial capabilities. The 3% impact on the housing market underscores the importance of being well-prepared.
Navigating the New Housing Market Landscape: Advice for Sellers
Sellers also need to adjust their strategies in light of the Federal Reserve’s interest rate hike. The market is shifting, and what worked a few months ago may not be effective now. The immediate 3% impact on the housing market requires a more nuanced approach. Here’s what sellers should consider:
- Price Competitively from the Start: Overpricing your home in a cooling market can lead to it sitting on the market for an extended period, eventually necessitating a price reduction that can signal desperation to buyers. Work with your agent to set a realistic and competitive price based on current market conditions and comparable sales.
- Focus on Presentation and Condition: In a market with fewer buyers and more inventory, homes that are well-maintained, updated, and staged effectively will stand out. Address any necessary repairs or cosmetic improvements before listing to maximize your home’s appeal.
- Be Prepared for Negotiation: Buyers now have more leverage. Be open to negotiating on price, contingencies, and even seller concessions (like covering closing costs). Flexibility can be the key to securing a sale.
- Understand Your Local Market: Real estate is hyper-local. While national trends provide a general overview, your specific neighborhood or city might be experiencing different dynamics. Your real estate agent can provide invaluable insights into local inventory levels, buyer demand, and recent sales data.
- Consider Marketing Strategies: Beyond traditional listings, explore professional photography, virtual tours, and targeted online advertising to reach a broader audience and highlight your home’s unique features.
- Don’t Panic Sell: While the market is shifting, it’s not collapsing. Avoid making hasty decisions based on fear. If you don’t need to sell immediately, you might consider waiting to see how the market stabilizes, though this comes with its own risks.
The goal for sellers is to adapt to the new realities, focusing on strategy and preparedness to achieve a successful sale in a less frenzied environment. The 3% impact on the housing market means that meticulous planning is more important than ever.
Long-Term Outlook: What This Means for the Future of Housing
While the immediate 3% impact on the housing market is a significant development, it’s also important to consider the long-term outlook. The Federal Reserve’s actions are designed to bring inflation under control, which, if successful, could lead to a more stable economic environment in the future. A period of moderation in housing prices, while potentially challenging in the short term, could ultimately lead to a more sustainable and healthy market over the long run.
Historically, housing markets tend to adjust to changes in interest rates. While sharp increases can cause a temporary shock, the market eventually finds a new equilibrium. This might involve slower price appreciation, increased inventory, and a return to more traditional market dynamics where buyers have more options and sellers need to be more strategic. The current adjustments could pave the way for a market that is less prone to speculative bubbles and more aligned with fundamental economic principles.
Furthermore, demographic trends, such as millennials entering their prime home-buying years, continue to provide underlying support for housing demand. While higher rates might delay some purchases, the long-term desire for homeownership remains strong. Innovation in housing construction, including modular homes and sustainable building practices, could also play a role in addressing affordability challenges over time, irrespective of interest rate fluctuations.
The Federal Reserve’s actions, therefore, are not just about short-term market corrections; they are part of a broader strategy to foster long-term economic stability. While the immediate 3% impact on the housing market certainly requires attention and adaptation, the future of housing will likely be shaped by a combination of these monetary policy decisions, evolving demographics, and ongoing innovation in the real estate sector. Adapting to these changes will be key for all stakeholders in the housing ecosystem.
Potential Opportunities Amidst the Shift
While an interest rate hike and its immediate 3% impact on the housing market often bring concerns, it’s also crucial to recognize the potential opportunities that can emerge during such a shift. For some buyers, a cooling market might present a chance to purchase a home without the intense bidding wars and waived contingencies that characterized the recent frenzied market. Less competition could translate to more time for due diligence, home inspections, and a greater ability to negotiate on price and terms. This could be particularly beneficial for patient buyers who have been priced out or outbid in previous market conditions.
For real estate investors, a market correction can create opportunities to acquire properties at more favorable valuations. Distressed sales, motivated sellers, or properties that have been on the market for an extended period might become available at prices that offer attractive returns, especially for those with access to capital or less reliance on high-leverage financing. Investors focused on long-term rental income might find that increased demand for rentals (as homeownership becomes less accessible) could stabilize or even boost their returns, provided acquisition costs are managed prudently.
Moreover, the shift could encourage innovation in the housing sector. Developers might explore more affordable housing solutions, new construction techniques, or alternative financing models to appeal to a broader range of buyers. The focus could shift from luxury developments to meeting the needs of a more price-sensitive market. This period of adjustment, while challenging, often fosters resilience and creativity within the industry, ultimately leading to a more robust and adaptable housing market in the long run. Identifying these opportunities requires a keen understanding of market dynamics and a willingness to adapt strategies to the new economic reality.
The Role of Government Policies and Local Markets
Beyond the Federal Reserve’s actions, it’s important to remember that government policies at federal, state, and local levels, as well as the unique characteristics of local markets, will also play a significant role in shaping the housing landscape. While the Fed’s interest rate hike has a broad impact, local factors can either amplify or mitigate its effects. For instance, areas with severe housing shortages might experience less of a price correction, even with higher rates, due to persistent demand and limited supply. Conversely, markets that have seen significant overbuilding or speculative activity might be more susceptible to price adjustments.
State and local governments can implement policies designed to support affordable housing, such as zoning reforms, tax incentives for developers, or first-time homebuyer assistance programs. These measures can help to counteract some of the negative effects of rising interest rates, providing a buffer for certain segments of the population. Understanding the interplay between national monetary policy and local governmental actions is crucial for a comprehensive view of the housing market.
Furthermore, economic diversity within a region can also influence its resilience. Areas with strong job growth and diversified industries might be better positioned to weather economic shifts compared to regions heavily reliant on a single industry. The 3% immediate impact on the housing market is a national average, but its manifestation will vary considerably from one metropolitan area to another, underscoring the importance of localized analysis for both buyers and sellers. Staying informed about both national economic trends and specific local conditions is paramount for making sound real estate decisions in this evolving environment.
Conclusion: Adapting to the New Reality of the Housing Market
The Federal Reserve’s recent interest rate decision marks a pivotal moment for the housing market. The immediate 3% impact on borrowing costs and affordability is already reshaping buyer behavior, seller expectations, and investor strategies. This move, aimed at curbing persistent inflation, signals a transition from a historically low-interest-rate environment to one characterized by higher borrowing costs and a more moderated pace of market activity.
For homebuyers, this means a renewed focus on budgeting, financial preparedness, and strategic patience. Sellers must adapt to a more competitive landscape, prioritizing competitive pricing and home presentation. Real estate investors and developers will need to recalibrate their financial models and explore new opportunities that emerge from a cooling market. While the short-term adjustments can be challenging, this period of recalibration could ultimately lead to a more balanced and sustainable housing market in the long run.
Navigating this new reality requires vigilance, informed decision-making, and a willingness to adapt. By understanding the profound implications of the Federal Reserve’s actions and staying abreast of both national trends and local market nuances, all participants in the housing ecosystem can better position themselves for success in the evolving landscape. The 3% impact on the housing market is not just a statistic; it’s a call to action for everyone involved to re-evaluate, strategize, and adapt.